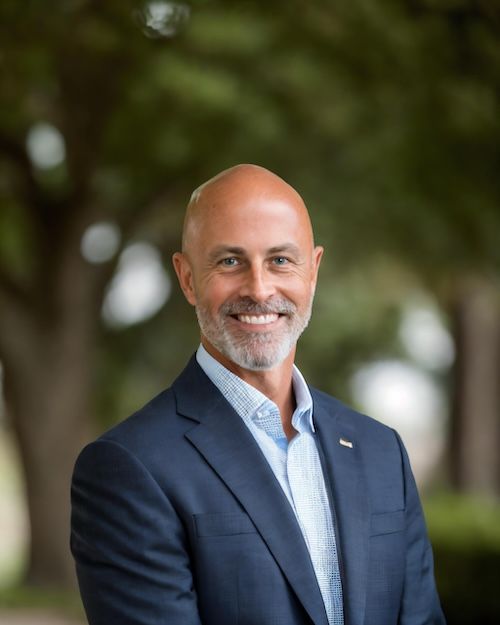
Do not make permanent financial decisions from a temporary emotional state. I say that as someone who had to learn it firsthand.
I have been through this
My marriage ended. I went through the separation, the divorce, and the several years on the other side of it that nobody warns you about.
I did the work. Therapy, and a fairly unflattering examination of my own part in how it ended. I dealt with the shame and the guilt and the stretch where I felt I had no control over anything. Inside that same period I also sold a company, changed industries, lost a job, and handled medical emergencies.
I am not telling you this to establish that I understand your feelings. I am telling you because of what I watched myself nearly do with money during it.
That is why I earned the Certified Divorce Financial Analyst® designation. Not from a marketing meeting. From having been the guy in the chair.
What divorce does to financial judgment
Divorce makes intelligent people do financially irrational things.
That is understandable. It is also expensive, and it is frequently permanent.
Here is the pattern. You are angry, you are grieving, and you are frightened, sometimes all inside the same hour. At the same moment, your entire financial life is being taken apart and reassembled by lawyers on a deadline. The decisions in front of you will shape the next thirty years, and you are being asked to make them at the worst cognitive moment of your adult life.
So people fight hard for the house, which they will not be able to carry alone. They trade away a retirement account because it feels abstract and the house feels like home. They spend six thousand dollars in legal fees winning a four-thousand-dollar argument. They concede something enormous because they want it to be over.
Every one of those is an emotional victory purchased with a financial loss, and every one of them is completely human.
The job is to separate the two. Not to stop you from feeling it. To make sure the feeling is not the thing signing the agreement.
Where the money gets decided
A few of the places where the difference between a good outcome and a bad one is largest:
The house. The most emotionally loaded asset and, often, the least suitable one to keep. Carrying costs, taxes, maintenance and the mortgage on one income change the picture considerably.
Assets that look equal and are not. $500,000 in a traditional IRA and $500,000 in a taxable brokerage account are not the same $500,000. One has a tax bill attached. Splitting “down the middle” without accounting for that hands one person a smaller settlement while both of you think it was fair.
Retirement accounts and QDROs. Dividing a 401(k) or pension has a procedure. Getting the mechanics wrong is costly and sometimes irreversible.
Support, and what it does to taxes. The rules changed in 2019 and a great deal of internet advice never caught up.
Insurance and beneficiaries. The line item everyone forgets until it becomes a problem for somebody else.
What your life actually costs after. Not a guess. A real number, run before you agree to anything.
None of that is legal advice, and I am not your attorney. I work alongside yours, doing the analysis so the two of you are negotiating from real numbers.
Why men specifically
Because that is who I am, that is the version of this I lived, and I would rather be useful to one group than vaguely useful to everyone.
Men in divorce also tend to arrive with a particular problem: they will discuss the settlement in detail and will not discuss anything else. Fewer people ask how they are doing. The tendency is to handle it alone, decide fast, and get it over with.
Deciding fast, in this situation, is the expensive move.
The part people do not believe at the time
There is a life on the other side of this that can be better than the one before it.
I did not believe that when I was inside it either. I believe it now, and I have watched enough clients get there to say it without overselling it.
What I can tell you is that the financial decisions you make during the next twelve months will have a great deal to do with which version of that life is available to you. That is the part I can help with.
What happens next
Step 1 — A virtual conversation. 30 minutes. No charge, no pitch. Bring whatever documents you have or bring none.
Step 2 — The analysis, in writing. What the proposed settlement actually means in numbers, and what your life costs afterward.
Step 3 — The rebuilding. Which is the longer part, and the one worth doing well.
Start a conversationA man’s financial guide to divorce